In a shifting financial landscape, the tightening of credit standards by U.S. banks is raising concerns among high-yield analysts. According to veteran analyst Marty Fridson, the recent Federal Reserve survey indicates that banks are implementing stricter lending criteria, particularly for medium and large companies. This shift could lead to increased default risks as borrowers face higher financing costs and global economic uncertainties. Despite some positive indicators, the tightening credit environment may soon result in more distressed debt opportunities, a scenario that has been relatively scarce in recent years.
Stricter Lending Standards Signal Potential Distress in Credit Markets
In the midst of a robust U.S. economy, a significant change is underway in the banking sector. In the fall of 2023, the Federal Reserve's latest survey revealed that banks have raised their lending standards to levels not seen in three years, especially for larger corporate borrowers. This move comes at a time when companies are already dealing with rising interest rates and global volatility due to trade tensions. Analysts warn that this tightening could push more firms into precarious financial positions, increasing the likelihood of defaults.
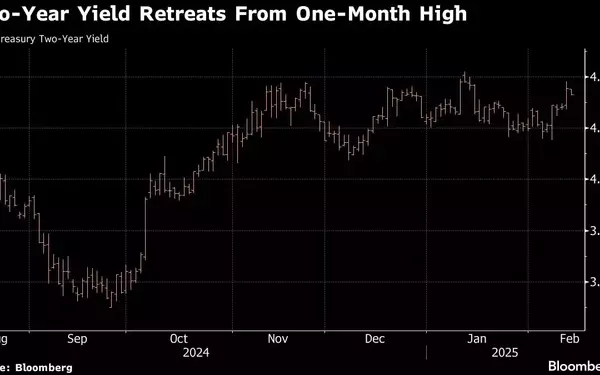
Marty Fridson, a respected figure in high-yield analysis, cautions that tighter credit conditions can exacerbate existing challenges for companies. As cheaper pandemic-era financing options expire, many businesses are finding it harder to refinance at affordable rates. Even though the Federal Reserve began cutting rates in September, benchmark yields like the 10-year Treasury have risen, making it tougher for lower-rated firms to navigate potential downturns. Fridson’s historical data shows a strong correlation between lending standards and market distress, suggesting that while immediate impacts may be delayed, an uptick in troubled debt is likely on the horizon.
Despite these warnings, some experts believe the current trend might be temporary. Since September 2023, lending standards have fluctuated, and if banks regain confidence in long-term growth prospects, they may loosen up again. Additionally, global demand for yield from U.S. issuers remains strong, providing a buffer for some struggling borrowers. However, the most vulnerable companies—those with impending debt maturities—are feeling the pressure acutely. Refinancing costs are soaring, and new policies on trade and immigration add further strain on input costs and earnings, creating uncertainty in the debt markets.
Corporate bond spreads remain tight, reflecting continued demand for high-yielding debt despite limited new supply. Yet, this apparent stability masks underlying vulnerabilities. Phil Brendel, a senior credit analyst, warns that prolonged low distress ratios could be a "tinderbox waiting to explode," especially given the volatile geopolitical climate. The stage seems set for an event that could disrupt markets more than anticipated, leaving many companies unprepared for the financial turbulence ahead.
From a journalist’s perspective, this evolving situation underscores the delicate balance between economic resilience and financial risk. While the U.S. economy has shown remarkable strength, the tightening of credit standards serves as a cautionary signal. It highlights the need for vigilance among investors and policymakers alike, reminding us that even in prosperous times, the seeds of future challenges can quietly take root. The coming months will reveal whether this tightening is a fleeting adjustment or a harbinger of broader shifts in the credit landscape.