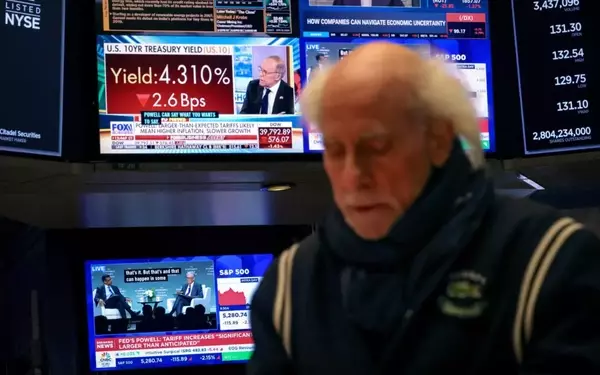
Financial disruptions often ripple far beyond their initial source, creating widespread effects. The 2008 financial crisis, for instance, started with subprime mortgages but quickly spread due to the interconnected nature of securitization. Similarly, while the dot-com crash remained relatively contained, other events like Thailand's currency devaluation in 1997 or Switzerland's move in 2015 demonstrated varying degrees of impact. Today, the introduction of tariffs by President Donald Trump has shifted focus from stock markets to bond markets, raising questions about potential broader consequences.
A major concern revolves around private credit, an expansive term encompassing loans managed by investment firms rather than traditional banks. These entities now hold over a trillion dollars more in loans compared to 2016, much of it issued during the booming years of 2021 and 2022. Critics argue that private credit is vast, untested, and lacks transparency, especially concerning efforts to attract retail investors. However, proponents highlight key differences between private credit and conventional banking practices. Investment funds typically use less leverage, maintaining a ratio of approximately one dollar of debt for every dollar lent, significantly lower than current bank standards. Additionally, many private loans are directed toward industries potentially better equipped to withstand economic shifts, such as software development and healthcare services.
While some private loans may indeed default, these instances represent isolated credit losses rather than systemic crises. Unlike traditional banks, private credit funds often operate with long-term capital commitments, reducing liquidity risks. This contrasts sharply with institutions like Silicon Valley Bank, which relied heavily on short-term deposits while investing in long-term assets. In conclusion, although challenges exist within the private credit sector, its structural differences suggest a reduced likelihood of triggering a broader financial meltdown. Instead, this highlights the importance of prudent risk management and regulatory oversight to ensure stability in evolving financial landscapes.